Thin Files, Thick Costs: The Borrower Data Gap Taxing CDFI Lending
Every CDFI loan begins with an act of reconstruction, as loan officers rebuild a borrower's financial picture by hand from scattered records. The data shows why that work is so heavy, and why the borrowers who need capital most are the hardest to see clearly.
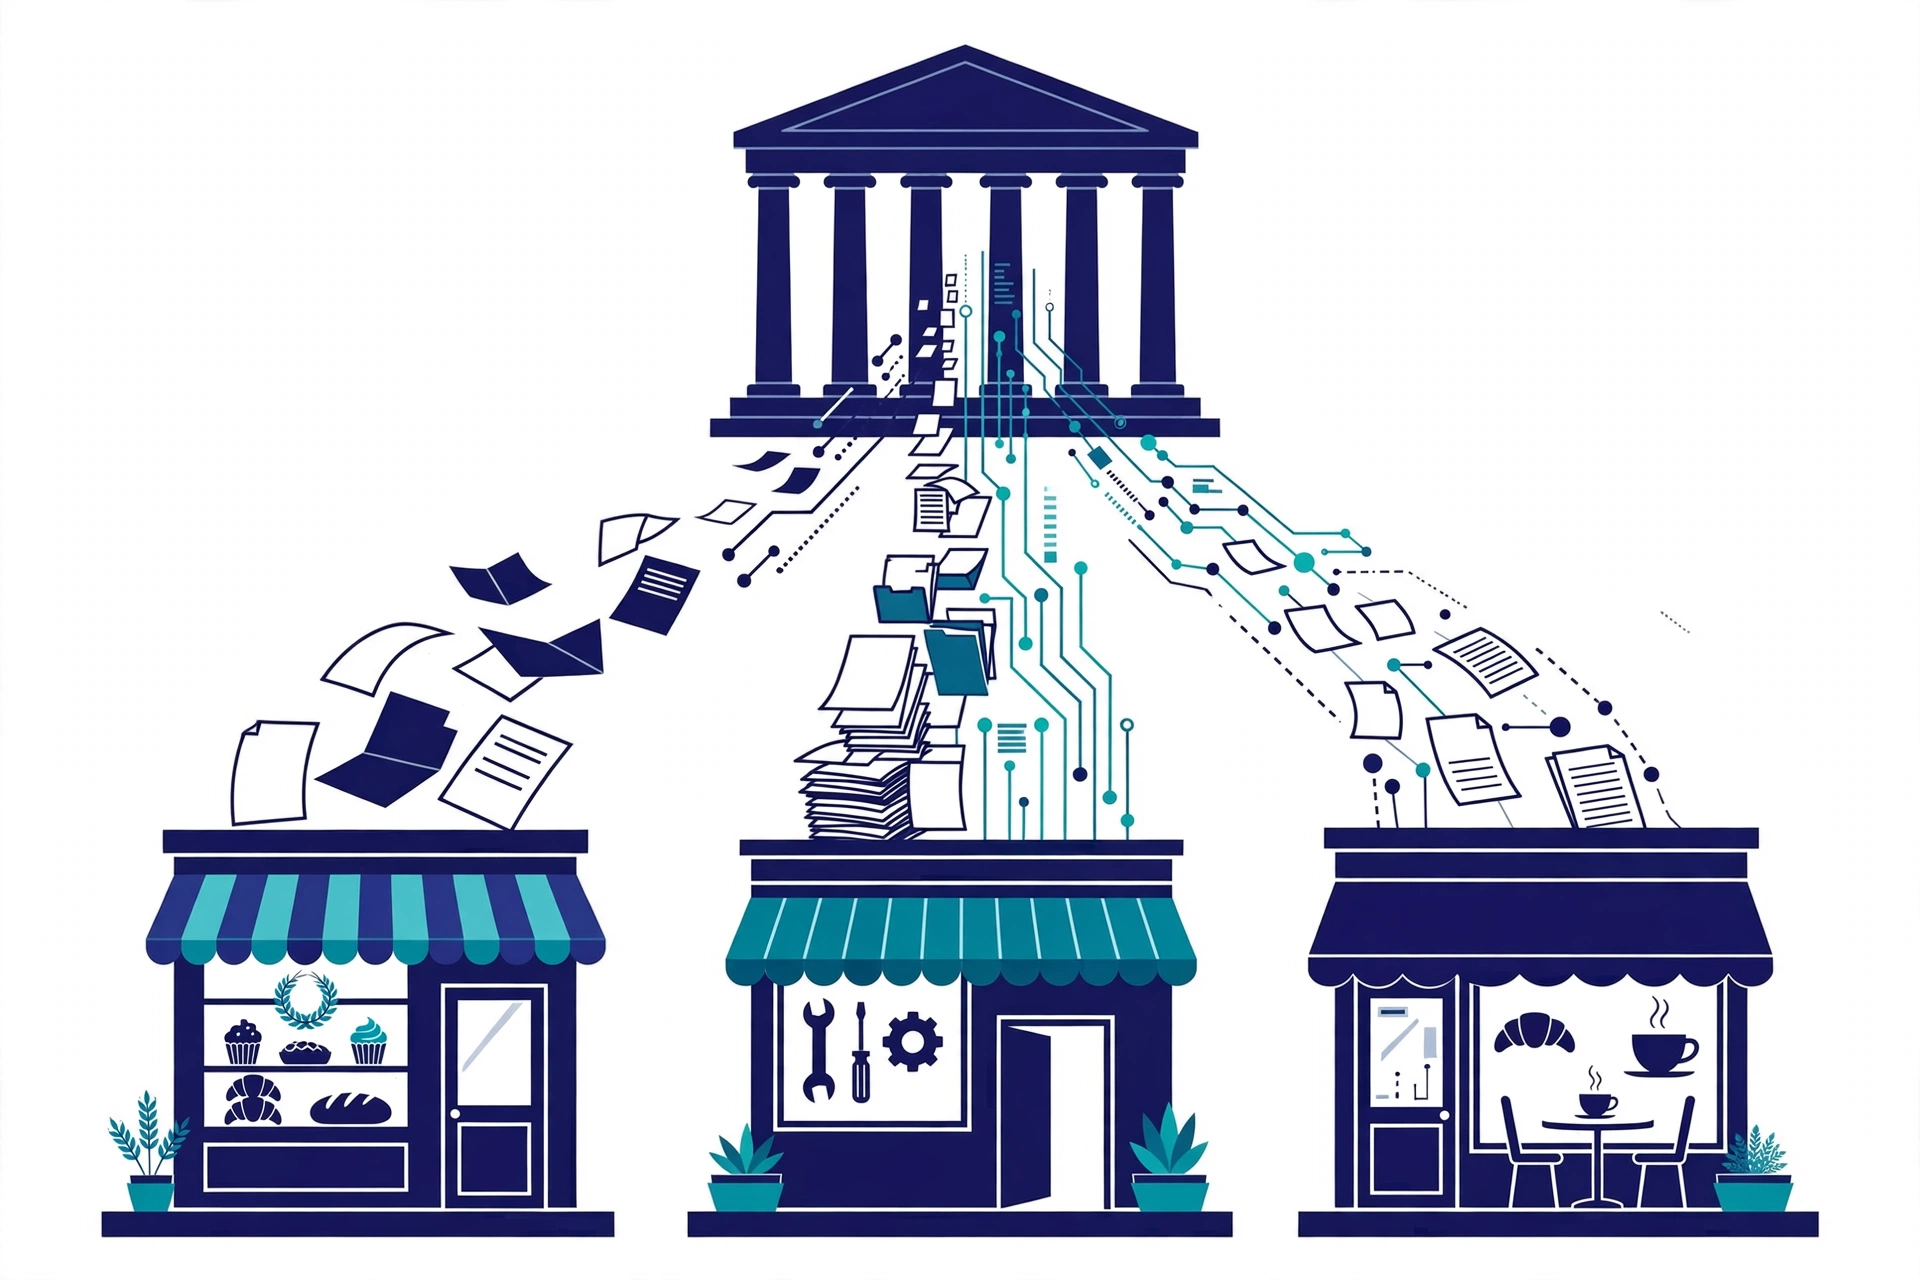
Ask a CDFI loan officer what the job actually consists of, and the honest answer is not lending. It is archaeology.
A prospective borrower arrives with a financial life scattered across systems that do not speak to each other: a point-of-sale report in one format, bank statements in another, invoices in a drawer, a tax return prepared months ago for a different purpose. Before a single credit judgment can be made, someone has to rebuild one coherent picture of the business out of those fragments. That reconstruction happens by hand, on nearly every file, and it happens again at renewal, again at monitoring, again at reporting time.
This is the borrower data gap, and it is the quietest cost driver in community development finance. It does not appear as a line item. It appears as loan officer hours, as turnaround times borrowers cannot wait out, and as a hard ceiling on how many businesses a CDFI can serve with the staff it has.
What the data says about the borrowers
The borrowers at the center of this work operate with remarkably little slack, and the research quantifies it.
The JPMorgan Chase Institute's study of 597,000 small businesses found that the median firm holds 27 cash buffer days: enough cash to keep paying outflows for 27 days if income stopped entirely. A quarter of firms hold 13 days or fewer. For first-year firms, the Institute's follow-up research found buffers of 12 days for Black-owned firms, 14 days for Hispanic-owned firms, and 19 days for white-owned firms.
The Federal Reserve's Small Business Credit Survey tells the same story from the borrower's side. In the 2024 survey, the most common financial challenges reported by employer firms were rising costs (75 percent), paying operating expenses (56 percent), and uneven cash flow (51 percent). In the pre-pandemic 2019 survey, only 14 percent of employer firms said they could absorb a two-month revenue loss using cash reserves alone, with no other action. Among even the healthiest firms, it was one in five.
Thin buffers are not a side detail in this data. In the Institute's survival analysis, cash buffer days and revenue predicted which firms exited the following year, and firms with limited buffers and irregular cash flows were the least likely to survive. For a mission lender, that means the borrowers most in need of patient capital are also the ones whose condition changes fastest, and whose paper file goes stale quickest.
Where the cost lands
The gap taxes a CDFI in three places.
First, underwriting. When the borrower's picture must be rebuilt manually for every application, cost per loan stays high regardless of loan size, which is the arithmetic that makes small-dollar lending so hard to sustain.
Second, monitoring. After closing, visibility into the borrower's condition becomes episodic: a quarterly check-in, an annual financial statement, a call when something already looks wrong. With a 12-day buffer, a borrower's situation can deteriorate completely between two check-ins.
Third, technical assistance. TA is the industry's signature intervention, and it is delivered largely one borrower at a time, often untargeted. Staff cannot easily tell which of two hundred borrowers needs help this month, so help goes to whoever asks loudest or whoever is already closest to the institution.
What structured borrower data would change
None of this requires speculation about technology. It requires one shift: borrower financial data arriving structured and current, with the borrower's consent, instead of reconstructed and stale.
Underwriting then becomes an exercise of judgment on top of a picture that already exists, rather than the labor of assembling the picture itself. Monitoring becomes early warning instead of post-mortem; a lender that can see a buffer shrinking in week two can act in week three. Technical assistance can be triaged, directed by evidence toward the borrowers the data flags, which is the only plausible path to TA that scales beyond staff headcount. And the reporting that funders and the CDFI Fund require becomes a byproduct of operations rather than a separate season of work.
The discipline matters as much as the data. Borrower consent and borrower ownership of their records are not features to bolt on; for institutions whose legitimacy rests on trust in the communities they serve, they are the whole foundation. Structured data gathered without that discipline would solve a cost problem by creating a trust problem, which is a trade no mission lender can afford.
The bottom line
The constraint on CDFI lending is often described as a shortage of capital. The data suggests a second constraint hiding underneath it: the cost of seeing clearly. Borrowers run on 27 days of cash, scattered records, and uneven flows. Lenders pay for that fragmentation on every file, every monitoring cycle, and every TA hour. Closing the borrower data gap will not capitalize a single loan fund by itself. But until it closes, every dollar of CDFI capital will keep paying a tax that has nothing to do with credit risk.
Sources
- JPMorgan Chase Institute, "Cash is King: Flows, Balances, and Buffer Days," September 2016. Farrell, Wheat & Mac, "Small Business Owner Race, Liquidity, and Survival," JPMorgan Chase Institute, July 2020. Federal Reserve Banks, 2025 Report on Employer Firms (2024 Small Business Credit Survey). Federal Reserve Banks, "Can Small Firms Weather the Economic Effects of COVID-19?" (2019 Small Business Credit Survey), April 2020.
Related coverage
 Data & Research
Small Business Loan Delinquencies Edge Up Across CDFI Portfolios, Survey Finds
By Pharoh Martin
 Policy & Regulation
CDFI Fund Opens FY2027 Financial Assistance Round With Expanded Persistent Poverty Set-Aside
By Pharoh Martin
 Lending Practice
How Loan Officers Are Rethinking Underwriting for Borrowers Without Credit Scores
By Pharoh Martin
The Weekly Briefing
What practitioners need to know, every Tuesday.
Policy changes, CDFI Fund notices, portfolio data and lending practice — written for executives, loan officers, policy staff and funders. Free.