ACCESS Financed the Contract, Not the Credit File: One Painter, 19 Deals, and a Run Toward $8M
A Nevada painting contractor with $120,000 in revenue won a hotel contract it could not afford to start. ACCESS CDFI financed about 80 percent of the contract value anyway, then repeated the deal 18 more times. The case, shared at a Federal Reserve symposium, is a clean look at what opportunity-based underwriting actually requires.
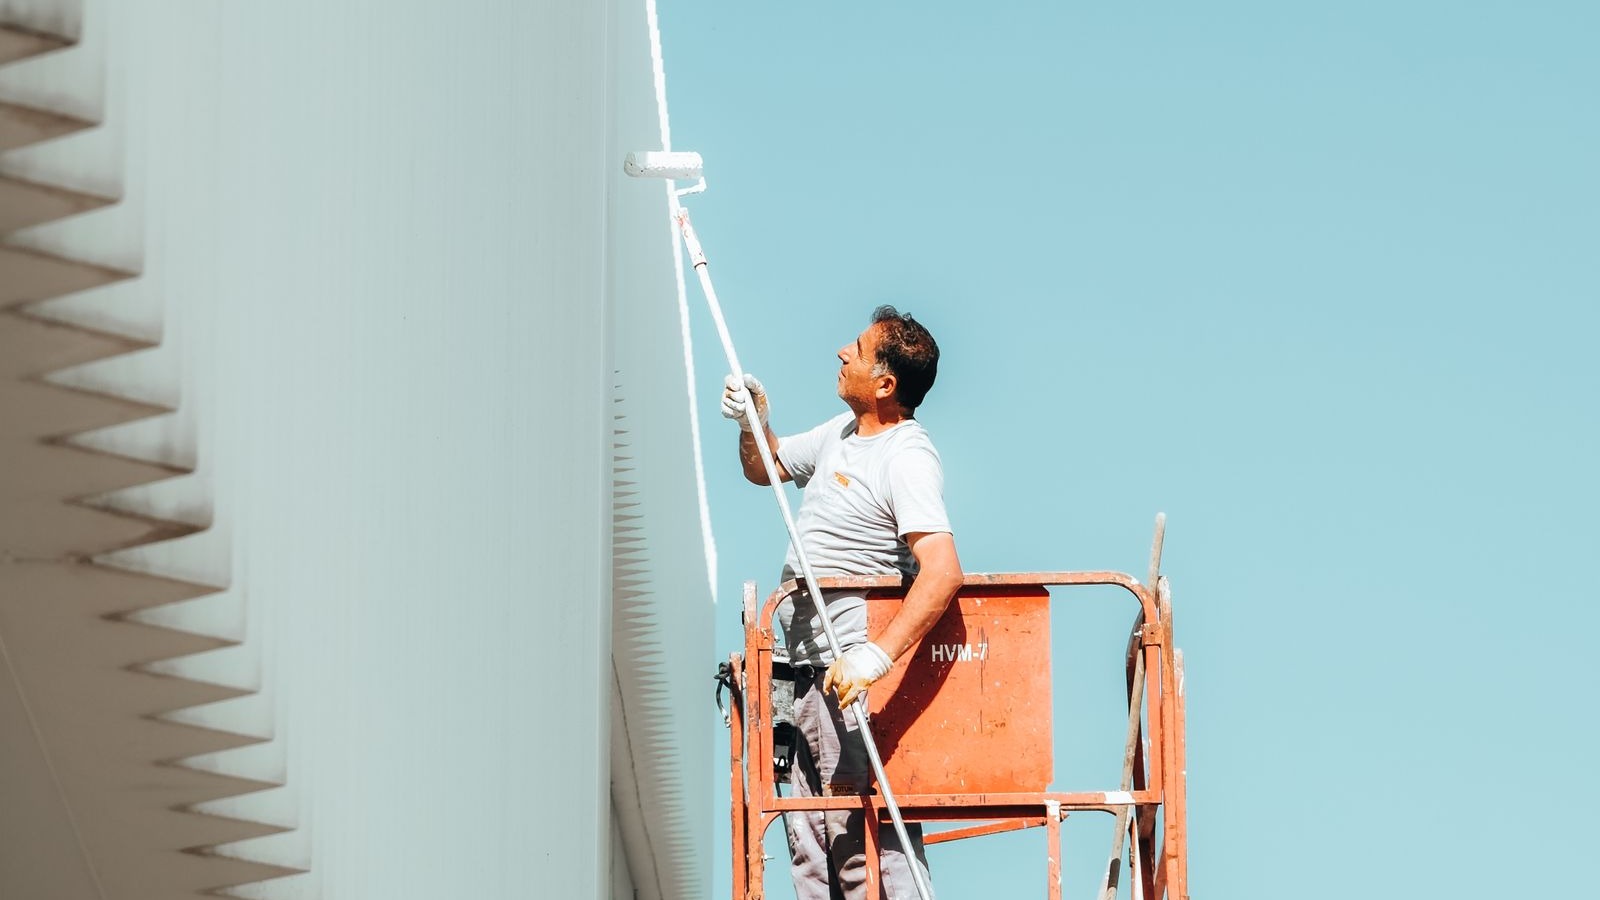
The borrower did not fit the box. A Nevada painting contractor with approximately $120,000 in annual revenue had won a contract to paint a hotel property, the kind of job that changes a small contractor's trajectory, and did not have the working capital to start it. Materials, payroll, and mobilization all come due before a contract pays. On a traditional underwriting read, the file ends there.
ACCESS CDFI, the only community loan fund headquartered in Las Vegas, read it differently. Rather than underwrite the borrower's history, the CDFI underwrote the opportunity in front of it, building a contract-financing product around the signed hotel job. ACCESS financed approximately 80 percent of the contract value, which gave the company the working capital to purchase inventory and hire employees to fulfill the commitment.
The result is the part that should get lenders' attention. ACCESS has since completed 19 contract-financing transactions with that same business, whose annual revenue is now projected to hit $8 million this year. The story was shared by ACCESS executive director Nic Steele at the Federal Reserve's State of Small Business Symposium and published by Fed Communities on October 15.
Underwriting the opportunity
Contract financing inverts the usual sequence of small business credit. A conventional loan asks whether the borrower's past supports the debt. A contract-financing structure asks whether the contract does: a signed agreement with a creditworthy customer, a defined scope, and a payment schedule that retires the advance as work is completed. The lender's risk sits less in the borrower's balance sheet and more in performance, which is a risk a lender can monitor job by job.
"The important lesson for us is that the growth didn't come simply from providing a loan," Steele said. "We understood the business, identified the specific barrier preventing the new work, and designed a capital solution that matched the opportunity."
That sentence carries the operating cost of this model. Opportunity-based underwriting is not a looser standard; it is a more labor-intensive one. Somebody has to understand the borrower's trade, the customer's payment behavior, and the gap between contract value and cash on hand. It does not scale through automation alone. It scales through a lender willing to do the analysis and a product designed for repeat use, which is exactly what 19 transactions with one borrower represents.
Technical assistance is part of the credit structure
Steele is explicit that the financing was not the whole intervention. ACCESS pairs lending with customized technical assistance and wraparound support, from bookkeeping and business planning to connections with partners when a need sits outside the CDFI's own services. "We started as a lender focused on providing access to capital, but it became clear very quickly that we needed to look beyond the loan itself and understand the circumstances of the business owner," Steele said.
In credit terms, that support functions as risk infrastructure. A borrower whose books, bidding, and cash management improve with every job is a better credit in transaction nineteen than in transaction one, and the revenue line shows it: from roughly $120,000 to a projected $8 million, with the same lender structuring each step. The founder's side of this story, and the playbook it suggests for landing a contract you cannot yet afford, is worth its own read.
The bottom line
Every CDFI knows a version of this borrower: real demand, a real contract, and a balance sheet too thin to perform it. The ACCESS case is useful because it isolates the decision. The barrier was never the borrower's ability to do the work. It was the timing of cash, and timing is a solvable underwriting problem for a lender built to solve it.
Sources
- Federal Reserve System, Fed Communities, "Small business ecosystem supports highlighted during Fed event," October 15, 2026 (reporting on the Federal Reserve's State of Small Business Symposium, including remarks by Nic Steele, executive director of ACCESS CDFI).
Related coverage
 Lending Practice
How Loan Officers Are Rethinking Underwriting for Borrowers Without Credit Scores
By Pharoh Martin
 Industry News
JPMorganChase Lends $10M to ACE, the Largest Lending-Capital Investment in the CDFI's 26 Years
By Pharoh Martin
 Data & Research
Thin Files, Thick Costs: The Borrower Data Gap Taxing CDFI Lending
By Pharoh Martin
The Weekly Briefing
What practitioners need to know, every Tuesday.
Policy changes, CDFI Fund notices, portfolio data and lending practice — written for executives, loan officers, policy staff and funders. Free.